
The Consumer Financial Protection Bureau (CFPB) has recently proposed changes to regulations governing overdraft fees.
This proposal aims to regulate overdraft fees and would limit institutions to only charge a fee in line with the overdraft cost or in accordance with an established benchmark. Under the benchmark fee approach, a large institution may presume that any charge or combination of charges it imposes for overdraws does not exceed its cost and charge-off losses for providing the overdraft credit if the charge or combination of charges is less than or equal to any benchmark fee established. The proposed benchmarks from the CFPB are as follows: $3, $6, $7, or $14 . An estimated 23 million households pay overdraft fees each year and this proposal expects to save consumers around $3.5 billion or more in fees. The CFPB notes that consumers are charged on average of $35 for an overdraft, even though majority of these overdrafts are for less than $26 and are repaid within three days. While only the largest credit unions and banks with $10+ billion in assets would be held to this regulation, it seems reasonable to expect that smaller exempt institutions will have to lower fees to encourage consumers to continue banking with them versus moving to a lower fee large institution.
Despite the consumer-centric intention, the CFPB’s proposal may not necessarily translate into favorable outcome for credit union members and bank customers. Regulation of overdraft fees could limit member access to credit and other essential financial services due to the interconnected nature of financial products and services. With a reduction in fee income, institutions will have to find other avenues to manage profitability, like increasing loan rates, or cutting consumer-centric products and services that are costly to maintain, making it a zero-sum game.
Exhibit 1
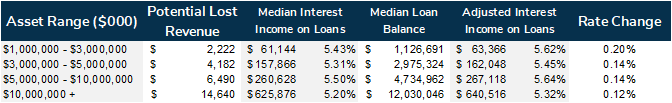
To adapt to the changing fee landscape, institutions will have to explore alternative strategies to increase income or reduce expenses. To make up the additional in non-interest income, institutions greater than $1 billion in assets would have to improve efficiency and reduce expenses by on average 14.67%. If financial managers decide to utilize interest income to replace fee income, loan rates across the board would have to increase somewhere between 12bps and 20bps for institutions greater than one billion in assets. Alternative strategies that drive fee income could potentially be utilized. Moving back to fee-based deposit accounts rather than free accounts to make up non-interest income through fees that are not considered “overdraft/NSF” could be an avenue that many adopt.
Exhibit 2
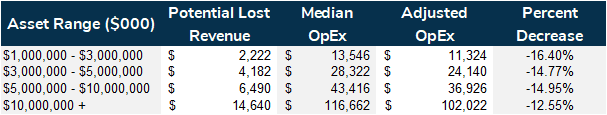
Exhibit 3
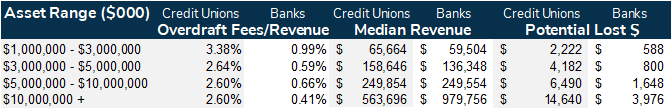
If one assumes that competitive pressure will fall down stream to smaller credit unions who might struggle to retain members or attract new members without following suite, it could create additional challenges for smaller institutions. Overdraft reporting is only mandated for credit unions with assets of $1 billion or more, the chart above suggests that smaller institutions rely more heavily on fee income. If extrapolated to institutions with assets under $1 billion, it can be inferred that the percentage of revenue that overdraft fees make up would be similar. The reduction in overdraft fee income diminishes a significant revenue source for these financial institutions which could hamper ability to compete. With reduced income, it is reasonable to expect smaller institutions to struggle and cause the downstream impacts consistent with less income.
Given the potential reduction in revenue, credit union leaders and financial managers need to continue to be diligent with loan pricing and think intentionally about how they allocate capital. Financial managers might have to review member giveback and the cost to the institution to determine if it is a cost the credit union can afford with lower income. Ultimately, while the CFPB’s proposal aims to protect consumers from excessive overdraft fees, it introduces several challenges for credit unions and smaller financial institutions. Industry leaders need to ensure they understand their exposure and have conversations with their Board regarding the optimal way to manage through this change to the industry.
