
The National Credit Union Administration (NCUA) released a letter announcing an expansion and revision to the procedures used to evaluate a credit union’s interest rate risk (IRR) exposure.
At a high-level, the changes include:
- Removal of the “Extreme” risk category
- Clarifying when a Document of Resolution (DOR) is warranted
- Enhancing flexibility in assigning IRR ratings
- Revising IRR examination procedures
Summary of Changes
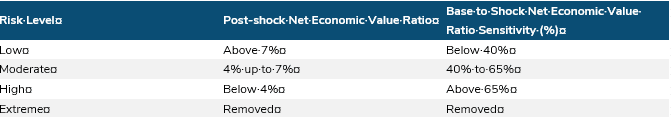
The most notable changes include the removal of both the “Extreme” category and the automatic DOR
resulting from a particular risk classification. No changes were made to the financial methodology of the
Net Economic Value (NEV) Supervisory Test. The “Extreme” category was simply removed, with “High”
now being the highest risk classification.
While a DOR will no longer be issued because of the test alone, considerations are made based on
factors such as capital, concentrations, liquidity, and others in conjunction with IRR. Interestingly,
examiners may now adjust the IRR rating classification up or down. In effect, this means even if the test
shows “Moderate” the examiner may use judgement, particularly in borderline cases, in assigning an IRR
rating.
Lastly, the revision of IRR procedures includes three examination components that will be necessary for
credit unions with a “High” classification and all credit unions above $10B in assets. These include:
- The source of IRR. High IRR results might stem from base net worth, concentrations, market environments, or several other combinations of factors. This is the qualitative assessment the examiner makes in understanding the IRR classification.
- Risk management and controls. Examiners will review the adequacy of policies and governance.
- This includes the control activities of initiating action to remain in policy and controlling the impact of market risk.
- Potential impact to earnings and capital. As part of their review steps, examiners will assess the level of earnings and capital at risk under various scenarios.
Our Take
For those who have followed the industry and the NEV Supervisory Test, the first two changes come as
no surprise. The NCUA was well aware of the increasing incidence of Extreme results due in large part
to rapidly rising interest rates. As such, the guidance gives enhanced flexibility in the assessment of risk,
with the Test serving appropriately as one of multiple factors.
Since a DOR is no longer an automatic result of the test, for credit unions finding themselves in the
“High” category the discussion now revolves around the source of the result and the quality of the IRR
management program. For many entities, a classification of “High” may be a temporary result as they
earn their way out and assets reprice. The intention is not to be heavy-handed, force investment sales,
or prompt aggressive and potentially costly risk mitigation actions. However, having appropriate risk
management tools in place is paramount to demonstrate that IRR management is under control.
Looking for a trusted partner to assist with risk management? Contact ALM First’s team of
experienced professionals today to discuss your credit union’s needs.
Click here to download the PDF Version of this article.
