The Kevin Warsh honeymoon period appeared to end at the July 29 FOMC meeting
The Fed held steady despite three dissenting votes in favor of a rate hike
While still noisy, the economy is on solid footing with multiple sources of optimism
Kevin Warsh’s honeymoon as Fed Chair was short-lived. Following the June 17 FOMC meeting, his emphatic focus on price stability, echoed in the official statement, drew a favorable market response: the Treasury curve flattened, the dollar strengthened, and inflation expectations fell. Warsh’s priorities center on long-term strategic changes to Fed communication, balance sheet use, data inputs, and the policy framework. These are valid pursuits, but markets are typically more focused on near-term action.
Despite a softer-than-expected June CPI, inflation measures remained well above the 2% target heading into the July 29 meeting, as they have for much of the past five years. Some participants viewed the meeting as an early test of Warsh’s resolve, though fed funds futures priced only a one-third probability of a hike—still unusually high uncertainty relative to the heavier forward-guidance era of the prior three chairs. The FOMC voted 9-3 to hold rates steady. The statement was nearly identical to June’s, which had passed 12-0. The hold itself was no surprise; Warsh’s press conference drew the bigger reaction.
Warsh seemed more focused on the work of the tasks forces, which could still take several months to formulate any recommendations, than he was on making any policy decisions in the present. In other words, Warsh had some very tough talk on inflation leading up to this meeting, and under the banner of no forward guidance, he failed to connect this hawkish view to any plan of action. Asked which inflation measure he relies on for the 2% target, he cited PCE as the official metric “for now,” adding that strategy could change after next January and that the task forces might weigh in.
Markets reacted poorly, raising the first “credibility” questions for the new regime. The 2s/10s curve steepened more than 10 bps and the Dow fell over 1,100 points (-2.2%). We hesitate to over-interpret a one-off reaction, but it underscores how market imagination fills the void left by diminished Fed guidance. What will the task forces recommend? Does Warsh want to blur inflation metrics to move the goalposts as conditions shift? These questions may be answered satisfactorily early next year—but will the Fed sit idle until then while inflation stays elevated? That uncertainty emerged from the July 29 meeting, and Treasury implied volatility has risen accordingly.
Sources of Optimism
Ample noise remains for market participants to navigate, most notably the Iran war and AI worries, but there’s plenty of positive economic news to note as well. The first estimate of Q2 GDP missed versus expectations (1.5% q/q vs. 2.0% q/q), but the lower figure was due primarily to a wider trade deficit and reduced government spending (nondefense). Real final sales to private domestic purchasers, which is GDP minus trade, inventories, and government outlays, rose 3.9% in Q2, the best quarter since Q2 2021. Besides strong consumer spending, business investment continued to be a notable contributor to overall GDP growth. In the prior two quarters, technology investment dominated the overall figures within GDP, but in Q2, the non-tech investments in structures, equipment, and R&D outlays surged and outpaced tech investment. R&D investments were likely boosted by changes in tax law last year, and perhaps some reduction in tariff and other policy uncertainty helped unleash pent-up capital expenditures.
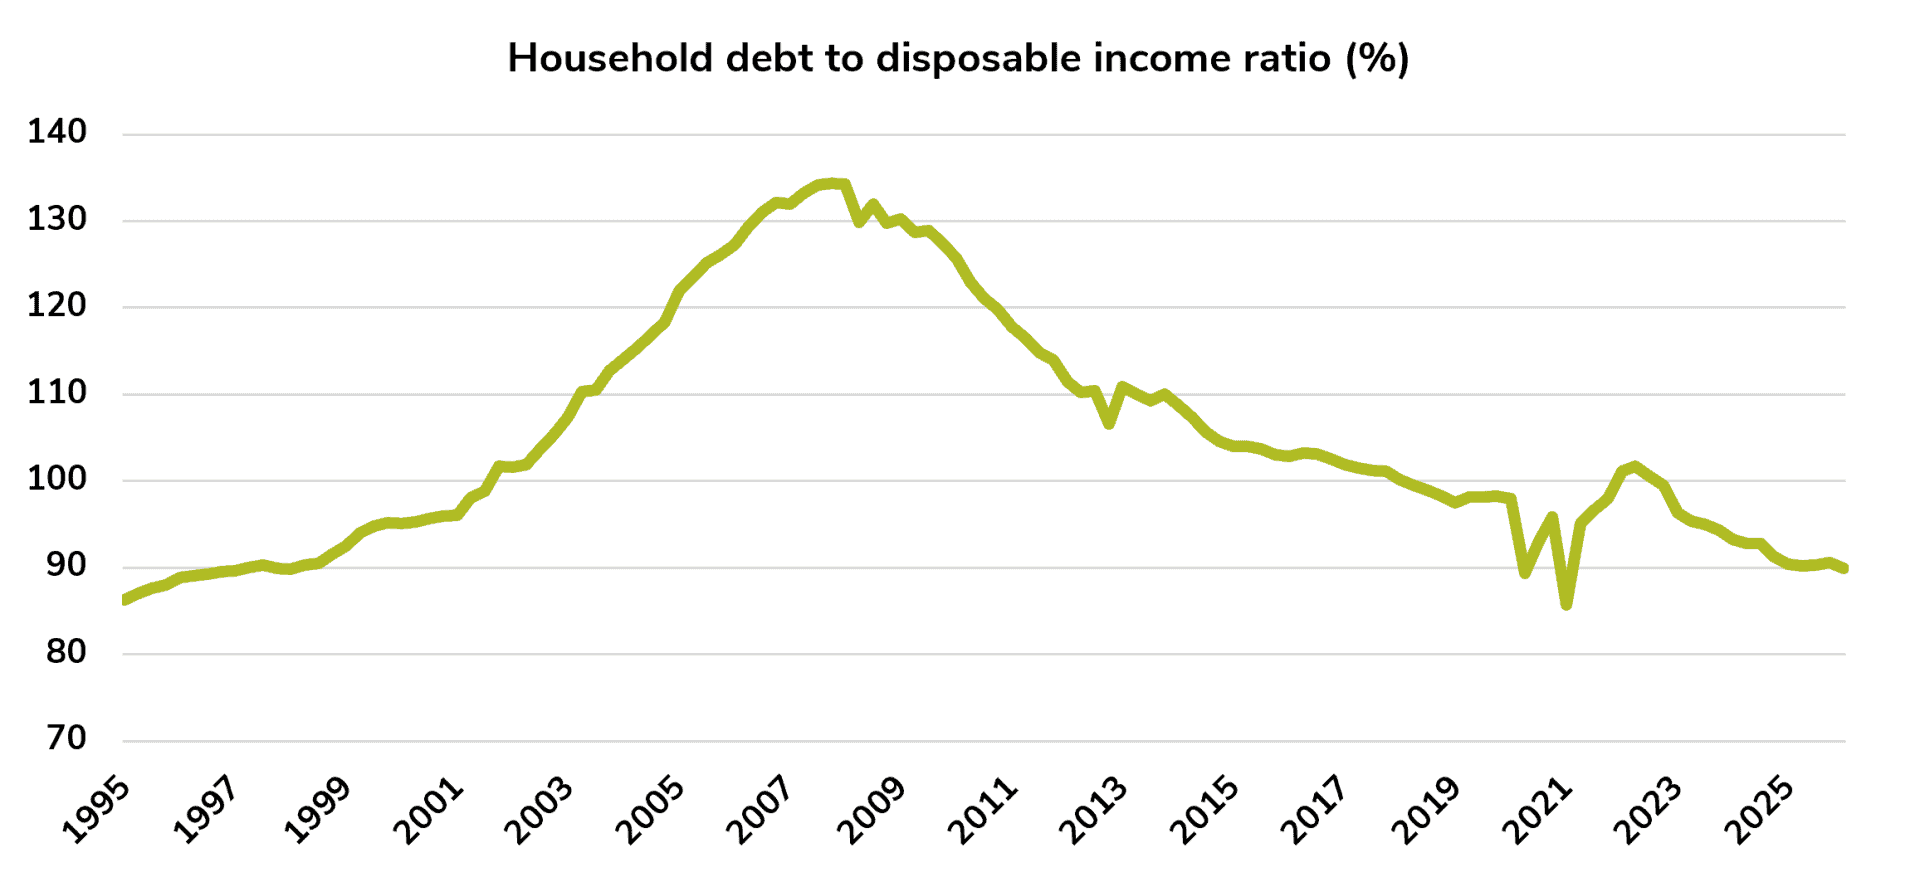
While business investment increases, consumer balance sheets remain generally in good shape. While inflation remains a concern, income and spending growth has been solid, and household leverage appears historically low. Exhibit 1 tracks the household debt to disposable income ratio, the latter of which measures income minus taxes. Other than the anomaly during the Covid era, the ratio has steadily fallen in recent years to the lowest level since the mid/late-1990s. This is not to suggest there are no economic potholes ahead, but current fundamentals for consumer balance sheets remain encouraging.
Exhibit 1
Source: Federal Reserve, Bloomberg, ALM First
To download the PDF of this econ only version, please click here.
To continue reading the full month’s market commentary, and to learn more about current market themes, market sectors, sector performances, and applied strategies, log in to the ALM First portal, and select this month’s commentary in the Resource Center.
If you do not have a login and you would still like to access the document, please send your inquiry to info@almfirst.com.