Site Search

Looking for something? Use the search bar below or visit our Resources page.


Author ALM First

Published

Estimated


Economic Update

  • Market sentiment improved in September, with investors seemingly shrugging off the latest negative trade headlines
  • Italian fiscal woes present another potential source of market volatility in the near term
  • The Fed continues to move forward with gradual policy tightening, and there were no major surprises from the September FOMC meeting

The tone in global risk markets was improved in September, with both Treasury yields and major equity markets higher over the month. Investors were largely dismissive of the announcement of more tariffs against China, and communication from Fed leaders following the September 26 FOMC meeting points to ongoing “gradual” policy tightening for the foreseeable future. On the trade front, President Trump hailed the finalization of USMCA, the new agreement with Mexico and Canada which will replace NAFTA, and the three country leaders expect to sign the agreement before the end of November. There are no signs of easing tensions with China, but the markets appeared to shrug off the latest escalation. On September 17, President Trump announced new tariffs on $200 billion of Chinese imports. The tariff rate begins at 10%, and on January 1, 2019, the rate climbs to 25%. If China were to retaliate, the president threatened to initiate a third phase of tariffs, which would include approximately $267 billion of Chinese goods. As expected, China did indeed retaliate by announcing new tariffs on $60 billion of U.S. goods.

It is now likely that the United States will apply tariffs on all goods imported from China (~$500 billion) at some point in 2019, and these actions should put upward pressures on producer and consumer prices (inflationary) and weigh, at least modestly, on economic growth. China will likely continue to respond with additional fiscal and monetary stimulus to offset the impact of the tariffs, which should put more downward pressure on its currency relative to the dollar. J.P. Morgan equity analysts project that 25% tariffs on all Chinese imports would reduce 2019 U.S. earnings per share growth from 10% to 5%, which they predict would be the final nail in the coffin for the long-running U.S. stock market rally (positive for U.S. rates, all else equal).

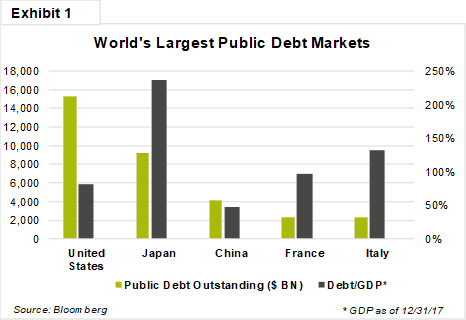
Beyond trade tensions, it’s also worth keeping an eye on developments in fiscal and political challenges for Italy. The country recently released budget deficit projections that were well above expectations and create more tensions with eurozone leaders in agreeing to a budget plan within currency union rules. As Exhibit 1 illustrates, Italy has one of the largest bond markets in the world, and of those markets, only Japan has a higher debt/GDP ratio. As such, Italy presents much greater risks to the global markets than Greece did several years ago. Because of this, European officials are far more motivated to compromise on an ultimate solution, but in the meantime, this situation could spark pockets of volatility and demand for U.S. Treasuries.

Fed Staying the Course

The Fed offered no real surprises at its September 26 FOMC meeting. While a rate hike was all but assured, there was some speculation in the market that the forward guidance might shift a bit more hawkish. However, Fed leaders appear content to maintain consistency in its 2018 mantra of “gradual” and deliberate normalization in an effort to stay ahead of inflation and financial stability risks. Following another 25 basis points (bps) increase in the target fed funds range, the updated Summary of Economic Projections (SEP) revealed that the median participant forecast still shows one more hike in 2018 and three more in 2019 (unchanged from June). The official statement only had one notable change: as some had anticipated, the committee removed the word “accommodative” from its assessment of current monetary policy, suggesting that Fed leaders believe current policies are close to neutral. This change does not infer that rate hikes will end soon, and it is more likely that policy will eventually move into restrictive territory, a point reinforced by the Fed’s projected hikes in 2019 and 2020 that would go beyond the long-term neutral policy rate. At the same time, the aggregate projections for economic data and the fed funds rate present the optimal soft landing for the U.S. economy, which is just short of finding a unicorn from an economic and monetary policy perspective.

The markets continue to underprice the Fed’s projected rate hikes in 2019 and beyond, which is consistent with what happened in the mature phase of the last tightening cycle in 2004-2006. The median FOMC participant forecast for the fed funds rate at the end of 2019 is 3.125% versus fed funds futures pricing at 2.82%. If the Fed does indeed drive short-term rates beyond what current forward rates would imply, floating-rate assets should continue to perform well relative to short-duration fixed-rate assets. There are several headwinds that could keep an effective cap on long-end yields, including geopolitics, trade tensions, etc.

Lastly, the FOMC also chose to raise the interest on excess reserves (IOER) rate by 25 bps at the September meeting. The effective fed funds rate had drifted higher in recent weeks to only 2 bps below IOER, sparking questions of whether the committee might choose to again just raise IOER by 20 bps and push it closer to the middle of the target range. That did not happen, and it will be interesting to read the minutes of the meeting to assess just how concerned, if at all, policymakers are with this issue. They were clear in the June decision that they would ideally like the effective rate to be in the middle of the target range, but as a market-traded rate, there is only so much the Fed can do to control the effective rate…


To continue reading this month’s market commentary, and to learn more about current market themes, market sectors, sector performances, and applied strategies, log in to the ALM First portal, and select this month’s commentary in the Resource Center.

ALM First

ALM First was founded in 1995 with the focus on financial advisory services for credit union clients.

LinkedIn

  Commentary Disclaimer

ALM First Financial Advisors is an SEC registered investment advisor with a fiduciary duty that requires it to act in the best interests of clients and to place the interests of clients before its own; however, registration as an investment advisor does not imply any level of skill or training. ALM First Financial Advisors, LLC (“ALM First Financial Advisors”), an affiliate of ALM First Group, LLC (“ALM First”), is a separate entity and all investment decisions are made independently by the asset managers at ALM First Financial Advisors. Access to ALM First Financial Advisors is only available to clients pursuant to an Investment Advisory Agreement and acceptance of ALM First Financial Advisors\' Brochure. You are encouraged to read these documents carefully. All investments involve risk and may lose money.

The content in this article is provided for informational purposes and should not be relied upon as recommendations or financial planning advice. We encourage you to seek personalized advice from qualified professionals regarding all personal finance issues. While such information is believed to be reliable, no representation or warranty is made concerning the accuracy of any information presented. Statements herein that reflect projections or expectations of future financial or economic performance are forward-looking statements. Such “forward-looking” statements are based on various assumptions, which assumptions may not prove to be correct. Accordingly, there can be no assurance that such assumptions and statements will accurately predict future events or actual performance. No representation or warranty can be given that the estimates, opinions or assumptions made herein will prove to be accurate. Actual results for any period may or may not approximate such forward-looking statements. No representations or warranties whatsoever are made by ALM First Financial Advisors as to the future profitability of investments recommended by ALM First Financial Advisors.

Moreover, this report was prepared as of the date indicated herein. No representation or warranty is made by ALM First that any of the returns or financial metrics detailed herein will be achieved in the future, as past performance is not a reliable indicator of future results. Certain assumptions may have been made in preparing this material that have resulted in the returns and financial metrics detailed herein. Changes to the assumptions may have a material impact on any returns or financial metrics herein. Furthermore, ALM First gives no representation, warranty or undertaking, or accepts any liability, as to the accuracy or completeness of the information contained this report. This report was prepared for informational purposes only without regard to any particular user’s investment objectives, financial situation, or means, and ALM First is not soliciting any action based upon it. This material is not intended as, nor should it be construed in any way as accounting, tax, legal, or investment advice including within the meaning of Section 975 of the Dodd-Frank Wall Street Reform and Consumer Protection Act. Certain transactions give rise to substantial risk and are not suitable for all investors. The strategies discussed herein can have volatile performance and may employ leverage. Moreover, investment advisory fees and expenses may offset trading gains. This report was prepared by ALM First Financial Advisors, LLC. The hereto mentioned report contains information which is confidential and may also be privileged. It is for the exclusive use of the intended recipient(s). If you are not the intended recipient(s), please note that any distribution, copying, or use of this report or the information contained herein is strictly prohibited. If you have received this report in error, please notify the sender immediately and then destroy any copies of it. ALM First neither owes nor accepts any duty or responsibility to the unauthorized reader. ALM First shall not be liable in respect of any loss, damage, or expense of whatsoever nature which is caused by any use the unauthorized reader may choose to make of this report, or which is otherwise a result of gaining access to the report by the unauthorized reader. This content contains information derived from third-party sources. We believe that this third-party data is reliable; however, we cannot guarantee this data’s currency, accuracy, timeliness, completeness, or fitness for any particular purpose.

INDEX BENCHMARKS: Index performance is discussed for illustrative purposes only as a benchmark for each strategy’s performance and does not predict or depict performance of that strategy. While index comparisons may be useful to provide a benchmark for a strategy’s performance, it must be noted that investments are not limited to the investments comprising the indices. Each of the strategy benchmark indices are unmanaged and cannot be purchased directly by investors.

HYPOTHETICAL PERFORMANCE DISCLAIMERS: Performance figures derived from model portfolios are hypothetical in nature and the results of any individual investor will differ as a result of various factors, including investment limitations relative to model portfolio guidelines, availability of same or similar assets, and fee structures. Investments are presumed to have been made at the beginning of the time period and there are no inflows or outflows of cash during the period. There are limitations and risks associated with the use of model performance or hypothetical performance information, and you should be cautious when looking at any presentation of model or hypothetical performance information. Investment strategies should not be based solely on the use of model or hypothetical information. Actual results will be different from those shown in model or hypothetical performance. The model portfolio returns reflect actual trading including the reinvestment of coupon payments and are net of transaction costs, administrative costs and a strategy-specific per annum fee ranging from 5 bps to 50 bps, which is the amount of the highest fee charged to any ALM First Financial Advisors, LLC customer employing that particular strategy during the period under consideration (the “Model Fee”). Actual fees will vary depending on, among other things, the applicable fee schedule and portfolio size. ALM First\'s fees are available upon request and also may be found in its Form ADV Part 2A. Past performance does not guarantee future results.


Strategic Partners

Let’s Work Together

ALM First is your agile partner with a trusted history of delivering results.
