
Site Search

Looking for something? Use the search bar below or visit our Resources page.


Author ALM First

Published

Estimated


Economic Update

  • Treasury yields reached 15-year highs across much of the curve in August
  • Economic optimism and rising U.S. budget deficits have pressured long-end benchmark yields higher in recent weeks
  • Community-based financial institutions are experiencing rising cost of funds and liquidity challenges, but profitability, loan growth, and credit metrics have held somewhat steady

Treasury yields reached 15-year highs across much of the yield curve in August with multiple factors contributing to the move. Overall, the economic data trends have surpassed expectations for more than three months and fueled the narrative that the Fed may indeed need to keep short-term rates ‘higher for longer,’ potentially leading to a higher long-run neutral policy rate. A common measure of this neutral, or natural, rate of interest in economic circles is r-star (r), a term that has emerged in discussions more in the last month than it has in over a decade. Loosely defined, r is the inflation-adjusted rate of interest that supports economic expansion at a target level of inflation. This metric is notoriously difficult to quantify in real time, but the general focus of market participants is whether this estimated rate is higher or lower than what is being priced into the term structure of interest rates at any given time. For example, market speculation that this figure will be higher in the future should lead to higher long-term benchmark yields, which are effectively forward expectations for short-term rates plus a term premium paid for greater interest-rate risk. Also pressuring intermediate and long-end yields in August was the Department of Treasury’s quarterly refunding announcement on July 31 that showed much higher funding needs for the government in Q3 and potentially beyond given rising budget deficits and other factors (discussed in the Current Market Themes portion of our August Monthly Market Update).

The difference between forward market pricing and Fed guidance has narrowed notably in recent weeks. Based on the June FOMC Summary of Economic Projections (SEP), the median fed funds forecast revealed a 5.625% terminal rate in 2023 and 100 basis points (bps) of rate cuts in 2024. In mid/late July, markets were pricing for no more rate hikes in 2023 and 150 bps of cuts in 2024, but as we begin September, the market is more aligned with the Fed. In his annual Jackson Hole speech on August 25, Fed Chair Powell offered no material revelations as to the current perspective of policymakers other than a firm commitment to return inflation to the 2% target rate. To get there, Powell said he and his colleagues still believe a period of below-trend economic growth, including a cooling of labor market conditions, will be necessary.

Even after considerable policy tightening and a mini crisis in the banking sector, the U.S. economy has remained resilient and in expansionary territory, albeit at a moderating pace. In the final week of August, the July JOLTS report revealed a significant drop in job openings to the lowest level since March 2021, and later that week, the headline unemployment rate rose 30 bps to 3.8%. However, the latter was attributable to a large increase in the official labor force as opposed to a decline in household employment. Growth in nonfarm payrolls exceeded expectations, and wage growth was in line with expectations.

What the path forward will be is a difficult question to answer for Fed policymakers and market participants alike. In the very near term, the Fed could justify another pause at the upcoming September FOMC meeting, but if the current data trend persists, it’s unlikely we’ve seen the final hike of the cycle. In reviewing the many uncertainties related to the economy during the Jackson Hole speech, Powell was adamant that “2% is and will remain our inflation target.” He also suggested that balancing the risks of doing too much or too little in the inflation battle is a complex task, but it would seem that Powell and the hawks of the committee are more concerned with doing too little at this point. This makes rate betting an even more perilous effort (and an unnecessary one for financial institutions) going forward. Markets are already priced for rate cuts next year, in line with Fed guidance from the June FOMC meeting. However, when the updated SEP is released following the September 20 FOMC meeting, the “dots” may very likely show less rate cuts in 2024 and beyond. At that point, market participants will choose whether to follow the more hawkish guidance, and if there are indeed no (or less) rate cuts in the near/intermediate term, then the entire Treasury curve would need to reprice accordingly.

Bank & Credit Union Trends

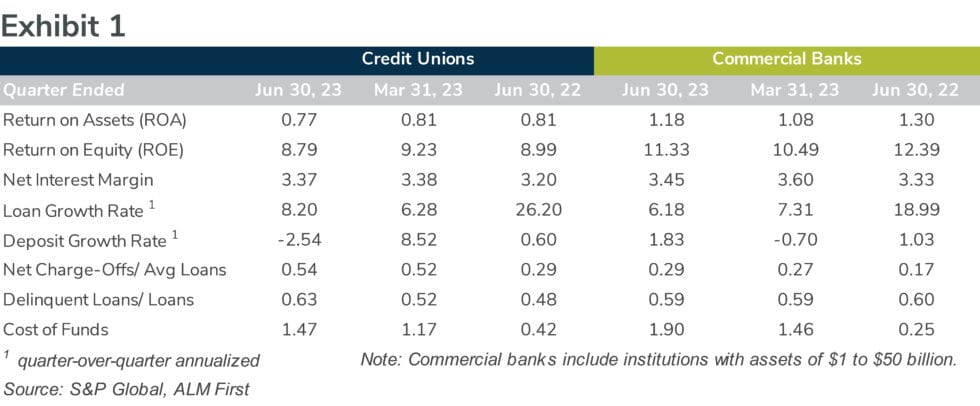
One major concern in the wake of the March bank failures was a tightening of credit conditions that would ultimately stifle economic growth. As noted in previous commentaries, the reduction in both demand for and supply of credit began in the second half of 2023 across multiple lending categories following record growth in the first half of last year. That trend continued in Q2, but as illustrated in Exhibit 1, loan growth remained in positive territory for community-based financial institutions, though at a slower pace relative to a year ago. The average cost of funds was notably higher over the quarter, but the average credit union net interest margin (NIM) was essentially unchanged at 3.37%. Average bank NIM fell 15 bps to 3.45%, both still above levels seen a year ago thanks in large part to higher asset yields and funding costs still lagging the market. On the credit front, the average percentage of delinquent loans held steady for banks at 0.59% and rose 11 bps to 0.63% for credit unions.
It’s likely still too early to wave the all-clear flag for financial institutions, particularly with the yield curve remaining steeply inverted. Some institutions lost sight of disciplined risk management amid the flood of monetary and fiscal stimulus in 2020 and 2021, and with marginal funding costs continuing to rise, it becomes more critical than ever to maintain discipline in all areas of funds management, including proper asset pricing in an ALM framework.


To download this economic update portion of our Monthly Market Commentary, click here.

To continue reading the full month’s market commentary, and to learn more about current market themes, market sectors, sector performances, and applied strategies, log in to the ALM First portal, and select this month’s commentary in the Resource Center. If you do not have a login and you would still like to access the document, please send your inquiry to info@almfirst.com.

ALM First

ALM First was founded in 1995 with the focus on financial advisory services for credit union clients.

LinkedIn

  Commentary Disclaimer

ALM First Financial Advisors is an SEC registered investment advisor with a fiduciary duty that requires it to act in the best interests of clients and to place the interests of clients before its own; however, registration as an investment advisor does not imply any level of skill or training. ALM First Financial Advisors, LLC (“ALM First Financial Advisors”), an affiliate of ALM First Group, LLC (“ALM First”), is a separate entity and all investment decisions are made independently by the asset managers at ALM First Financial Advisors. Access to ALM First Financial Advisors is only available to clients pursuant to an Investment Advisory Agreement and acceptance of ALM First Financial Advisors\' Brochure. You are encouraged to read these documents carefully. All investments involve risk and may lose money.

The content in this article is provided for informational purposes and should not be relied upon as recommendations or financial planning advice. We encourage you to seek personalized advice from qualified professionals regarding all personal finance issues. While such information is believed to be reliable, no representation or warranty is made concerning the accuracy of any information presented. Statements herein that reflect projections or expectations of future financial or economic performance are forward-looking statements. Such “forward-looking” statements are based on various assumptions, which assumptions may not prove to be correct. Accordingly, there can be no assurance that such assumptions and statements will accurately predict future events or actual performance. No representation or warranty can be given that the estimates, opinions or assumptions made herein will prove to be accurate. Actual results for any period may or may not approximate such forward-looking statements. No representations or warranties whatsoever are made by ALM First Financial Advisors as to the future profitability of investments recommended by ALM First Financial Advisors.

Moreover, this report was prepared as of the date indicated herein. No representation or warranty is made by ALM First that any of the returns or financial metrics detailed herein will be achieved in the future, as past performance is not a reliable indicator of future results. Certain assumptions may have been made in preparing this material that have resulted in the returns and financial metrics detailed herein. Changes to the assumptions may have a material impact on any returns or financial metrics herein. Furthermore, ALM First gives no representation, warranty or undertaking, or accepts any liability, as to the accuracy or completeness of the information contained this report. This report was prepared for informational purposes only without regard to any particular user’s investment objectives, financial situation, or means, and ALM First is not soliciting any action based upon it. This material is not intended as, nor should it be construed in any way as accounting, tax, legal, or investment advice including within the meaning of Section 975 of the Dodd-Frank Wall Street Reform and Consumer Protection Act. Certain transactions give rise to substantial risk and are not suitable for all investors. The strategies discussed herein can have volatile performance and may employ leverage. Moreover, investment advisory fees and expenses may offset trading gains. This report was prepared by ALM First Financial Advisors, LLC. The hereto mentioned report contains information which is confidential and may also be privileged. It is for the exclusive use of the intended recipient(s). If you are not the intended recipient(s), please note that any distribution, copying, or use of this report or the information contained herein is strictly prohibited. If you have received this report in error, please notify the sender immediately and then destroy any copies of it. ALM First neither owes nor accepts any duty or responsibility to the unauthorized reader. ALM First shall not be liable in respect of any loss, damage, or expense of whatsoever nature which is caused by any use the unauthorized reader may choose to make of this report, or which is otherwise a result of gaining access to the report by the unauthorized reader. This content contains information derived from third-party sources. We believe that this third-party data is reliable; however, we cannot guarantee this data’s currency, accuracy, timeliness, completeness, or fitness for any particular purpose.

INDEX BENCHMARKS: Index performance is discussed for illustrative purposes only as a benchmark for each strategy’s performance and does not predict or depict performance of that strategy. While index comparisons may be useful to provide a benchmark for a strategy’s performance, it must be noted that investments are not limited to the investments comprising the indices. Each of the strategy benchmark indices are unmanaged and cannot be purchased directly by investors.

HYPOTHETICAL PERFORMANCE DISCLAIMERS: Performance figures derived from model portfolios are hypothetical in nature and the results of any individual investor will differ as a result of various factors, including investment limitations relative to model portfolio guidelines, availability of same or similar assets, and fee structures. Investments are presumed to have been made at the beginning of the time period and there are no inflows or outflows of cash during the period. There are limitations and risks associated with the use of model performance or hypothetical performance information, and you should be cautious when looking at any presentation of model or hypothetical performance information. Investment strategies should not be based solely on the use of model or hypothetical information. Actual results will be different from those shown in model or hypothetical performance. The model portfolio returns reflect actual trading including the reinvestment of coupon payments and are net of transaction costs, administrative costs and a strategy-specific per annum fee ranging from 5 bps to 50 bps, which is the amount of the highest fee charged to any ALM First Financial Advisors, LLC customer employing that particular strategy during the period under consideration (the “Model Fee”). Actual fees will vary depending on, among other things, the applicable fee schedule and portfolio size. ALM First\'s fees are available upon request and also may be found in its Form ADV Part 2A. Past performance does not guarantee future results.


Strategic Partners

Let’s Work Together

ALM First is your agile partner with a trusted history of delivering results.